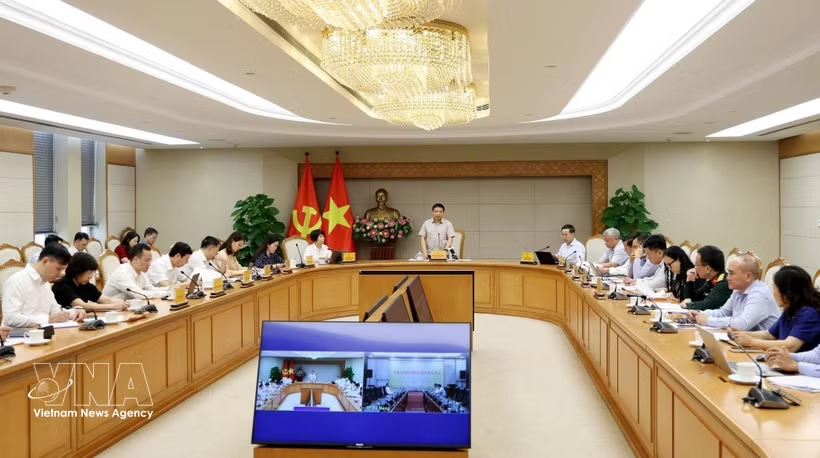
Hanoi (VNA) – Vietnam aims to complete preparations for its international financial centre in Ho Chi Minh City and Da Nang in October and attract initial transactions in November, Deputy Prime Minister Nguyen Van Thang said at a meeting on October 22.
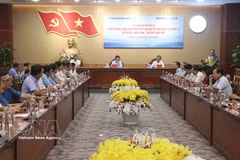
Thang, who is also Chairman of the Executive Council of the Vietnam International Financial Centre (VIFC), presided over the council’s fourth meeting in Hanoi, calling for coordinated efforts to ensure the centre operate effectively, safely and in line with the planned schedule.
He tasked the operating agencies in both cities with completing the necessary conditions in October and working directly with financial institutions and investors to attract members and generate transactions in November, while ensuring legal compliance and financial security.
According to reports presented at the meeting, the Ministry of Finance (MoF) has worked with relevant agencies to advise the Government on consolidating the executive council, issuing a development plan for the international financial centre through 2035, and finalising their operating regulations. The operating agencies in both cities have also agreed on application forms for membership registration and recognition.
The two cities have approved staffing arrangements and allocated personnel, funding, offices and technology infrastructure. They have also promoted investment overseas, with banks, securities companies, asset management organisations and investors signing memoranda of understanding, making commitments or submitting applications.
To prepare for initial transactions, MoF leaders have held direct discussions with commercial banks and financial institutions to identify deals that could be implemented soon.
At the meeting, representatives of the operating agencies in Ho Chi Minh City and Da Nang reported on progress and received feedback from ministries and agencies. The MoF proposed standardising operational procedures, one-stop services, membership criteria, reporting requirements, coordination between the two locations and the division of financial products between them.
Concluding the meeting, Thang praised the efforts made by ministries, agencies and the two cities, while urging them to accelerate outstanding tasks and resolve delays and bottlenecks.
He instructed the MoF to coordinate with the State Bank of Vietnam and relevant agencies to clearly define their respective responsibilities and powers, ensuring effective inspection, supervision and risk control without overlapping duties. Supervisory bodies must become operational before substantive transactions begin, Thang noted.
He also called for progress reports on the establishment of an arbitration centre and a specialised court, urging relevant agencies to bring these institutions into stable operation as soon as possible.
Regarding new financial products, Thang said products traded at international financial centres across the world could be considered for Vietnam if they suited local conditions and the country's capacity to manage risks.
In the initial phase, the MoF will work with the two cities to develop selected products and transactions in consultation with investment funds, investors and businesses. Priority will be given to transactions that connect capital providers with borrowers and support medium- and long-term funding needs.
Thang stressed the need for flexibility, practical implementation and timely adjustments rather than rigidly adhering to the initial product list.
He also directed ministries and agencies to promptly address proposals from the operating agencies and the MoF, review relevant regulations and propose necessary amendments, using expedited procedures where permitted by law. The aim is to prevent institutional obstacles from delaying products and transactions that are ready for implementation./.