Prime Minister suggests raising Vietnam – Oman Investment Fund’s scale to 1 billion USD

Emphasising that these investments have not only created economic values but also contributed to improving public services, social infrastructure development, and enhancing people’s quality of life, the PM proposed Oman expand and raise the scale of the fund to 1 billion USD to better support Vietnam’s investment and development needs, in line with its economy’s scale and with interest rates suitable to Vietnam’s conditions.

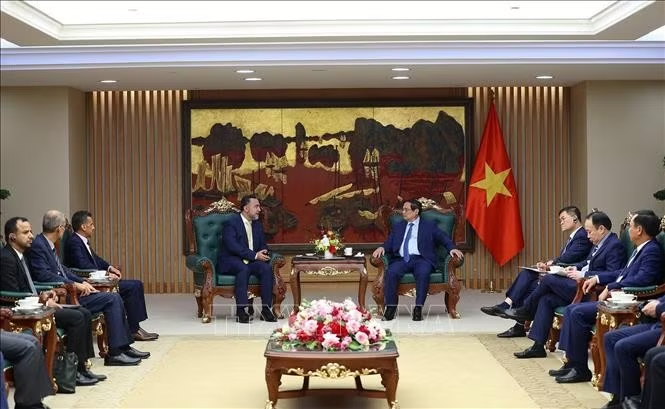
Prime Minister Pham Minh Chinh receives Sheikh Nasser bin Suliman Al Harthi, Deputy President for Operations of Oman Investment Authority (OIA) in Hanoi on May 29. (Photo: VNA)

Hanoi (VNA) – Prime Minister Pham Minh Chinh proposed Oman raise the scale of the Vietnam – Oman Investment (VOI) Fund to 1 billion USD while receiving Sheikh Nasser bin Suliman Al Harthi, Deputy President for Operations of Oman Investment Authority (OIA) in Hanoi on May 29.

PM Chinh hailed the OIA Deputy President’s working visit in the context of increasingly strengthened and flourishing Vietnam – Oman relations across many fields, especially in investment and economic cooperation.

Describing Oman as one of the leading potential partners in the Middle East region, he expressed his delight at the positive results of cooperation between Vietnam and the Arabian country, underlining that there remains considerable room for expanding bilateral collaboration.

The PM noted that at the recent 2nd ASEAN – Gulf Cooperation Council (GCC) Summit, he met and exchanged views with the GCC Secretary-General and leaders of the Gulf nations. Both sides highly agreed to promptly start negotiations on a Vietnam – GCC free trade agreement, study investment protection agreements, and promote cooperation in different fields such as digital transformation, renewable energy, financial centres and green economy, high-tech agriculture, and Halal food.

The Vietnamese leader acknowledged and highly valued the pioneering, effective, and strategic role of the Vietnam – Oman Investment Fund during more than 17 years of operations in Vietnam. The fund demonstrates a long-term vision, sustainable investment thinking, and a commitment to accompanying Vietnam’s socio-economic development with a selective, focused, and transparent investment approach.
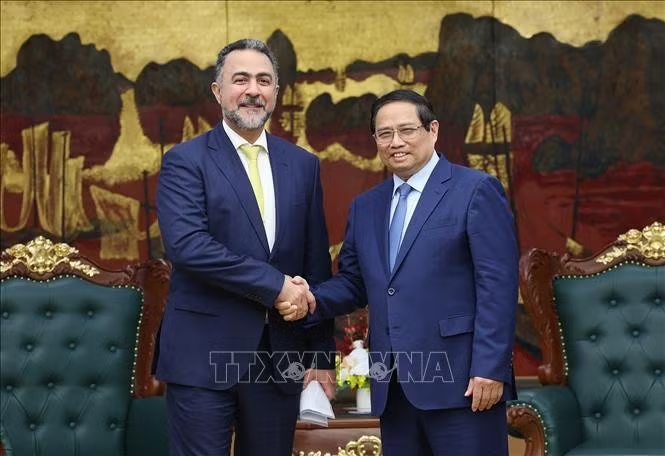
vna-potal-thu-tuong-tiep-pho-chu-tich-co-quan-dau-tu-oman-stand-1.jpg
Prime Minister Pham Minh Chinh (R) receives Sheikh Nasser bin Suliman Al Harthi, Deputy President for Operations of Oman Investment Authority (OIA) in Hanoi on May 29. (Photo: VNA)

Emphasising that these investments have not only created economic values but also contributed to improving public services, social infrastructure development, and enhancing people’s quality of life, the PM proposed Oman expand and raise the scale of the fund to 1 billion USD to better support Vietnam’s investment and development needs, in line with its economy’s scale and with interest rates suitable to Vietnam’s conditions.

PM Chinh suggested the fund not only support and invest in strategic fields such as infrastructure transport, clean water, renewable energy, healthcare, education, and consumer finance, but also participate in supporting Vietnam’s private economic development, as well as agriculture and the Halal food sector. He expressed confidence that with strategic partners like Oman, the two countries will build a deeper, more effective, and sustainable cooperation relationship.

For his part, Suliman Al Harthi emphasised Oman’s focus on enhancing cooperation with Vietnam, especially in investment - a highly potential and bright area in the bilateral relations in recent times.

The OIA Deputy President said that the OIA has collaborated with the State Capital Investment Corporation (SCIC) to establish the Vietnam new era growth fund with a minimum capital of 200 million USD. He confirmed that the fund will prioritise investment in potential sectors such as technology, telecommunications, finance, Halal agriculture, and digital transformation in Vietnam, contributing to strengthening trade exchange between the two countries.

Agreeing with PM Chinh’s proposal, especially on raising the VOI’s scale, Suliman Al Harthi said Oman can become a gateway for Vietnam to penetrate the Middle East market.

The OIA commits to further strengthening cooperation with Vietnamese partners, ready to play a bridging role in promoting economic and investment cooperation between the two countries, encouraging more Oman and Middle Eastern enterprises to explore cooperation opportunities in Vietnam, as well as calling on Vietnamese businesses to leverage Oman’s port system to boost exports to the Middle East region, he added./.
VNA

See more

Activities in Chan May Bay, part of the Chan May–Lang Co Economic Zone in Hue city. (Photo: VNA)

Hue steps up investment drive in Chan May–Lang Co Economic Zone

Covering more than 27,000ha, the Chan May–Lang Co Economic Zone is emerging as a key economic, urban, industrial and eco-tourism centre in southeastern Hue, with functional areas dedicated to seaports, industry, non-tariff activities, urban development and tourism.

The Ministry of National Defence's inter-agency inspection team visits La Gi Fish Port in Phuoc Hoi ward, Lam Dong province. (Photo: VNA)

Lam Dong's IUU fishing prevention efforts inspected

According to the Lam Dong provincial IUU Fishing Prevention Steering Committee, all 8,177 fishing vessels measuring at least 6 metres in length have been registered and updated in the national fisheries database VNFishbase.

A member of Minh Quang Cooperative in Hung Yen province works on a farm. (Photo: VNA)

Vietnam aims to link half of farm cooperatives with enterprises by 2030

The Ministry of Agriculture and Environment will promote links between cooperatives, enterprises, science and technology organisations and other economic entities along with carrying out programmes to develop concentrated agricultural, forestry and fisheries raw material areas and enhance value chain production.

The night-time economy is increasingly seen as an important avenue for Vietnam’s tourism sector to extend visitors’ stays (Photo: VNA)

Revitalising growth momentum for night-time economy

The night-time economy has moved beyond being merely an add-on service to become a new growth driver for tourism. Night-time activities can “awaken” familiar heritage spaces and breathe new life into them. Art, light and music experiences after dark can create distinctive attractions while meeting the desire of middle- and high-end visitors to explore cultural depth.

A livestream session promotes green-skinned pomelos grown in Cho Lach commune, Vinh Long province. (Photo: VNA)

E-commerce reshapes rules of game

Once fixed fees, payment fees, infrastructure charges and service packages are included, sellers may have to spend around 24.5-27.6% of their revenue on platforms. The figure shows that the era of easy selling and low costs in e-commerce has officially come to an end.

Ho Chi Minh City targets third-quarter growth of over 11% (Photo: VNA)

Ho Chi Minh City targets third-quarter growth of over 11%

Ho Chi Minh City will continue to implement drastic measures to achieve double-digit growth, targeting GRDP growth of at least 11.07% in the third quarter of 2026, 9.43% in the first nine months and 12.3% in the fourth quarter, with a view to completing the full-year goal of 10% or more.

MM Mega Market An Phu supermarket in Ho Chi Minh City is brightly decorated for the National Day holiday. (Photo: VNA)

Domestic consumption up over 13%, tourism continues strong growth

The total retail sales of goods and consumer service revenues in August were estimated at 679.8 trillion VND (26 billion USD), up 1.6% from the previous month and 14.9% year-on-year. In the January-August period, the figure reached 5.24 quadrillion VND, representing a 13.3% increase year-on-year.

A production line of Onaga Co., Ltd. (Japan) at HANSSIP (Photo: nhandan.vn)

Hanoi moves to maintain appeal to FDI inflows

In the first eight months of 2026, the capital city attracted more than 3.7 billion USD in FDI, equivalent to 83% of the plan set for the year. Newly registered FDI exceeded 572 million USD across 450 projects, up 175.78% in project numbers and 209.46% in capital compared to the same period last year. Additional registered capital topped 492 million USD, while capital contributions and share purchases exceeded 2.6 billion USD.

Saigon Marina IFC is the first private-sector project contributing to realising the goal of developing the Vietnam International Financial Centre in Ho Chi Minh City. (Photo: VNA)

VIFC offers various opportunities to attract forein investment

Turning the VIFC into an effective channel for international capital will require clear rules, quality projects and strong connections between investors and domestic businesses. Meeting these requirements will be key to transforming investor interest into concrete capital flows and investment projects in Vietnam.

Production line at Yadea Vietnam’s smart manufacturing plant, which has an investment of more than 100 million USD, in Tan Hung Industrial Park, Bac Ninh province. (Photo: VNA)

Development model for new era – An inevitable trend

International organisations broadly agree that shifting the growth model from reliance on traditional factors toward technology and innovation is no longer an option for Vietnam, but an imperative of the times.

At a commune administrative service centre in Hung Yen province (Photo: VNA)

Government determined to cut administrative procedures to drive double-digit growth

Resolution No. 258/NQ-CP, dated August 31, 2026, calls for substantive and comprehensive reform, with a focus on maximum cuts and simplification of administrative procedures and business conditions. It also seeks to shift management from pre-licence inspection to post-licence inspection based on risk management, while strengthening real-time, data-driven oversight and putting people and businesses at the centre of public services.