Hanoi (VNA) – Vietnam is moving to link green credit with its carbon market, a step expected to free up additional funding for the green transition and give banks a firmer basis to assess and manage capital flows to emissions-reduction projects.
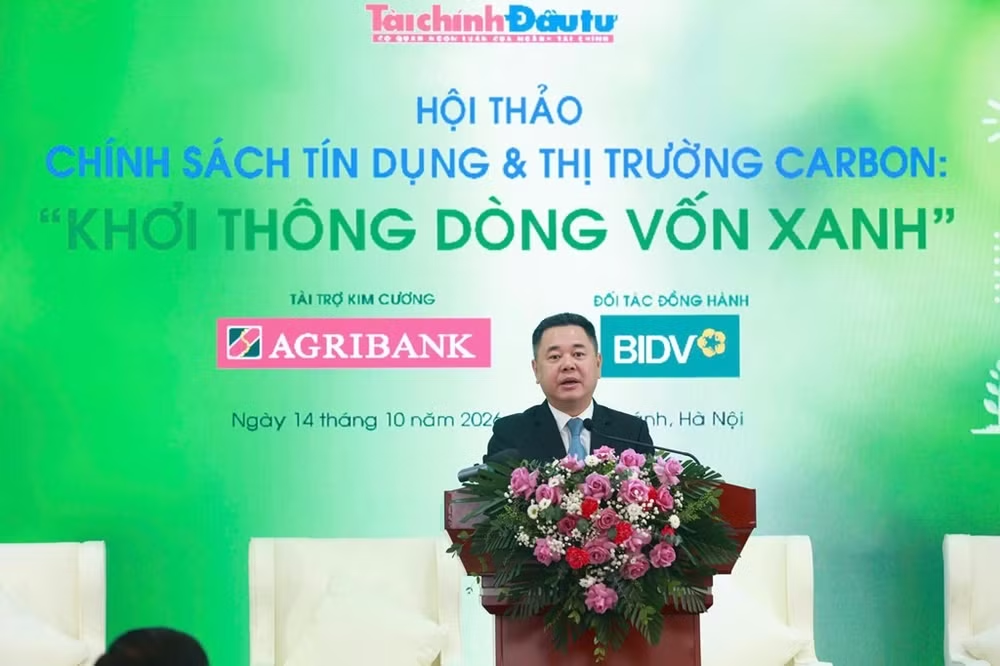
The issue was among those discussed at a seminar in Hanoi on October 14, co-hosted by Tai chinh – Dau tu (Finance and Investment) newspaper and the State Bank of Vietnam (SBV).
Green credit lays groundwork for carbon market
In his opening speech, Pham Van Hoanh, the newspaper’s Editor-in-Chief, said Vietnam is progressively finalising policies on green growth and its goal of net-zero emissions by 2050. The domestic carbon market began a pilot on June 29, 2026, raising the need to deepen links among green credit, banking system and new financial instruments.
SBV Deputy Governor Nguyen Ngoc Canh said meeting the 2050 net-zero pledge will require enormous resources for technological innovation, production overhaul, energy efficiency and emissions cuts. Alongside the State budget and capital and monetary markets, the carbon market is an important mechanism to raise additional funds, he said.
The Government issued Decree 29/2026/ND-CP on the domestic carbon exchange on January 29, setting the legal framework for the market and trading greenhouse gas emission allowances and carbon credits. The pilot market was launched with more than 511 million metric tonnes of CO₂ in allowances, allocated to facilities in three emissions-intensive sectors for 2025-2026, including thermal power, iron and steel, and cement. The pilot runs through the end of 2028, with full mandatory operation starting in 2029.
Canh said green credit funds the projects, technologies and sectors that deliver emissions cuts, while the carbon market can turn those cuts into economic value. If it works well, the market can generate extra revenue and cash flow, improving credit quality and helping companies meet environmental standards for exports.
Outstanding green credit across the banking system topped 856 trillion VND (32.9 billion USD) at the end of June 2026, up 9.87% from end-2025. From 2017 to 2025, green credit grew by more than 20% a year on average, focusing on agriculture, forestry, fisheries, biodiversity and green energy.
Proposal to connect carbon value chain
Dr. Nguyen Thi Thu Ha, Director of the Agribank Training School and deputy head of its ESG team, said the issue isn’t whether banks directly trade carbon credits. What matters is how they finance the creation of emissions reductions, and when carbon value becomes reliable enough to factor into lending decisions.
Agribank said financing needs emerge before any credits exist. Projects pass through preparation, investment, operation, measurement, reporting and verification (MRV), credit issuance, trading and settlement. That gap gives banks room to offer credit, bridge financing, cash flow management, guarantees and blended finance.
The lender proposed drawing clear lines among emissions-reduction potential, registered projects, verified results, issued credits, carbon-credit sales contracts and proceeds already collected. Each carries a different level of certainty and can’t automatically be treated as the same source of debt repayment.
Agribank identified five roles for banks in the carbon ecosystem, including financing emissions-reduction activities, linking stakeholders across the value chain, providing payment and cash-flow services, pooling climate finance, and supporting companies and individuals through the transition.
As an immediate step, it proposed a framework for identifying emissions-reduction projects and a set of criteria for assessing carbon-related credit. It suggested piloting value chains where emissions can be clearly gauged, such as low-emission rice, livestock and biogas, sustainable forestry, waste treatment and biomass energy. Banks also need to build partner networks, train interdisciplinary staff and strengthen data and governance systems.
Agribank plans to focus on data, capacity, partnerships and pilot models in 2026-2028, scale up in 2029-2032 as the domestic market becomes more stable, and study products based on carbon-related cash flows or receivables from 2033.
To support market growth, Agribank recommended clarifying ownership, disposition rights and benefit-sharing for emissions-reduction results and carbon credits, and completing rules on receivables, collateral, accounting, taxation and foreign exchange. It also called for treating data and MRV systems as market infrastructure, cutting verification costs, developing supply and demand together, and applying blended finance and risk-sharing mechanisms.
Canh said an effective carbon market lets companies convert emissions cuts into financial resources of their own, which could ease pressure on green credit. Rather than relying mainly on their own capital, State funding or bank loans to finance the transition, firms gain greater capacity to generate funds from their own emissions reductions./.